What Families Need to Know About Creditors After a Death
Understanding Creditors During Probate is an important part of settling an estate in Georgia. After a loved one dies, unpaid credit cards, medical bills, loans, taxes, mortgages, and other financial obligations may still exist. At the same time, family members may be grieving and trying to understand what happens to the person’s property.
The good news is that families do not have to figure everything out at once. The probate process gives the estate a legal framework for identifying assets, addressing debts, communicating with creditors, and eventually distributing property to the appropriate heirs or beneficiaries.
A key person in this process is the personal representative. Depending on the circumstances, this may be an executor named in a will or an administrator appointed by the probate court. Georgia law gives personal representatives responsibilities for administering the estate, including dealing with claims made by creditors.
This guide explains creditors during probate in simple language. It focuses on what families should know when a creditor sends a bill, how claims against an estate are handled, why records matter, and why relatives should be careful before paying a deceased person’s debts with their own money.
The goal is not to make probate sound complicated. Instead, it is to give families a clear starting point for understanding estate administration and knowing what questions to ask.
Understanding Creditors During Probate: Why It Matters
A Creditor Letter Does Not Mean You Should Panic
One of the first things a family may notice after someone dies is that the mail keeps coming.
A credit card statement may arrive. A medical provider may send a bill. A mortgage company may request payment. A collection agency may contact the family. These communications can be upsetting, especially when the family is still dealing with the loss.
However, receiving a bill does not automatically mean that a family member personally owes the money.
Generally, the estate is the starting point for addressing the deceased person’s valid obligations. The personal representative manages the estate and works through the applicable process for identifying and resolving claims.
Georgia law provides a procedure for creditors to notify a personal representative of claims against an estate. Georgia legislation provides that the personal representative publishes notice to creditors and gives them an opportunity to notify the representative of their claims. The law also allows the personal representative to request reasonable additional proof or an accounting supporting a claim.
That is why a creditor’s letter should usually be treated as important paperwork, not as an automatic instruction for a family member to write a personal check.
If your family is receiving creditor letters, collect them in one place and give them to the personal representative. If a debt is large, disputed, or connected to a house or other major asset, consider obtaining Georgia probate legal advice before making a payment.
Read our blog What is Georgia Probate Inventory. Learn what important documents to collect and why organizing these records can help families understand what the estate owns and owes.
What Is an Estate Creditor?
An estate creditor is generally a person or organization claiming that the deceased person or the estate owes money.
Creditors can include many different types of businesses and individuals. For example, an estate may receive claims involving medical care, credit cards, personal loans, mortgages, vehicle loans, utilities, taxes, or services provided before death.
Not every claim is automatically valid.
The personal representative may need to determine whether the debt belongs to the deceased person, whether the amount is correct, whether supporting documentation exists, and whether the claim should be paid from estate assets.
This is one reason estate administration is more than simply collecting money and giving it to heirs. The personal representative has to identify financial obligations and follow the rules that apply to the estate.
The Georgia Attorney General’s Consumer Protection Division explains that debt collectors may communicate with an executor of an estate and that federal and state protections apply to certain collection practices.
If a creditor contacts your family, avoid making promises about payment until you know who is legally responsible for the debt and how the claim fits into the estate.
Read our article Why Probate Notice Matters to Families to understand how to prepare if there are claims against the estate from creditors. Learn how notice can affect deadlines, creditor claims, beneficiary rights, and the administration of the probate estate.
How Estate Administration Handles Creditor Claims
Once probate or estate administration begins, the personal representative generally needs to develop a picture of the deceased person’s financial situation.
That means looking for known debts and watching for claims from creditors.
The process can involve several steps.
Finding the Deceased Person’s Debts
Families should begin by gathering financial records.
A useful search may include:
- Credit card statements
- Medical bills
- Mortgage statements
- Vehicle loan records
- Personal loan documents
- Utility bills
- Tax notices
- Insurance records
- Collection letters
- Bank statements
- Business-related debts
- Property-related expenses
The purpose of this list is not to suggest that every item automatically becomes an estate debt. Instead, these records help the personal representative identify possible obligations and determine what needs further review.
Reviewing Claims Against an Estate
A creditor may submit information showing that money is owed. The personal representative should keep a record of each claim and the documents supporting it.
Georgia law provides procedures concerning creditor notification and proof of claims. The statutory process is designed to give the estate a way to identify and address creditor demands rather than simply paying every invoice that arrives.
For families, this means organization is extremely important.
A simple creditor log can include:
- Creditor name
- Account number
- Type of debt
- Amount claimed
- Date of the claim
- Supporting documents received
- Contact information
- Whether the claim is disputed
- Payment status
- Notes about communication
Keeping this information together helps prevent duplicate payments and makes it easier to see which issues still need attention.
Valid Debt Versus a Questionable Claim
A creditor’s demand should not automatically be treated as proof that the estate owes the exact amount claimed.
For example, a statement might contain an incorrect balance. A medical bill might need insurance adjustments. A debt could have been paid before death. A collection agency might have incomplete information.
Therefore, the personal representative may need to request additional documentation.
Georgia’s creditor-claim provisions specifically recognize the personal representative’s ability to require reasonable additional proof or an accounting in connection with a claim.
This does not mean the personal representative should ignore legitimate creditors. Instead, it means that estate creditors should be handled in an organized and legally appropriate way.
How Families Can Make Creditor Administration Easier
The emotional side of probate can make paperwork difficult. Families may be dealing with funeral arrangements, property, insurance, family disagreements, and many other responsibilities.
A simple system can make the financial side easier.
Create a Creditor File
Start one physical or digital folder for creditor information.
Place copies of bills, statements, letters, and other documentation in the folder. Keep original legal documents in a secure location when appropriate.
Then create a separate list showing the status of each creditor.
This matters because an estate may receive multiple letters from the same company. Without a tracking system, a family could accidentally respond several times or lose track of an important notice.
Separate Estate Debts From Personal Debts
One of the most important ideas in Understanding Creditors During Probate is the difference between an estate obligation and a family member’s personal obligation.
A child is not automatically responsible for a parent’s individual debt merely because they are the child.
Likewise, being the executor does not simply transform all of the deceased person’s debts into the executor’s personal debts.
However, individual responsibility can exist in certain circumstances. For example, a person who was a joint borrower, co-signer, or otherwise legally obligated under a contract may have separate responsibility.
Because contracts and account ownership differ, families should not assume that every situation has the same answer.
Do Not Confuse an Executor With a Debtor
An executor or administrator acts on behalf of the estate.
That role involves administration. It does not automatically mean the person personally owes every debt belonging to the deceased.
This distinction can be especially important when a creditor contacts a family member who happens to be the executor.
The Georgia Attorney General’s consumer guidance specifically identifies an executor of an estate as someone with whom a debt collector may communicate concerning an alleged debt.
However, communication about an estate debt is not the same thing as establishing the executor’s personal liability.
Keep Communication in Writing
Telephone calls can be difficult to track. Whenever appropriate, families should preserve written communications from creditors and copies of responses.
For each communication, record:
- Date
- Creditor
- Account number
- Name of the person contacted
- Reason for the communication
- Information requested
- Response received
- Next step
This record can become valuable later if there is a disagreement about what was said or provided.
What Happens When a Debt Collector Contacts the Family?
A debt collector may contact people concerning a deceased person’s debt, but there are rules governing debt collection.
The Georgia Attorney General explains that the Fair Debt Collection Practices Act covers certain personal, family, and household debts and prohibits specified deceptive, unfair, or abusive practices. The guidance also explains that debt collectors may communicate with an executor of an estate.
If a collector contacts someone who does not believe they are personally responsible for the debt, the person should be careful about making statements that could create confusion about personal liability.
If a debt is disputed, federal and state procedures may provide rights concerning verification and collection activity. Georgia consumer guidance explains that certain written disputes can require a debt collector to provide verification before continuing collection efforts on the disputed amount.
The important family lesson is simple: do not ignore creditor communications, but do not automatically accept personal responsibility either.
A Helpful Comparison: Estate Responsibility and Personal Responsibility
The following table can help families understand why account ownership matters.
| Situation | General issue to review | Family should consider |
|---|---|---|
| Credit card only in deceased person's name | Possible estate debt | Give the statement to the personal representative |
| Joint credit account | Other account holder may have contractual obligations | Review account documents |
| Co-signed loan | Co-signer may have personal responsibility | Review the loan agreement |
| Medical bill in deceased person's name | Possible claim against the estate | Preserve bills and insurance information |
| Mortgage | Debt may be secured by property | Do not ignore mortgage notices |
| Vehicle loan | Debt may be secured by vehicle | Review loan and title information |
| Unknown collection claim | Claim may require verification | Request appropriate documentation |
| Bill paid before death | May not be a current estate debt | Confirm the payment and retain supporting records |
This table is a general educational guide. The actual result depends on the account agreement, ownership, estate documents, applicable law, and individual circumstances.
A Family Checklist for Managing Estate Creditors
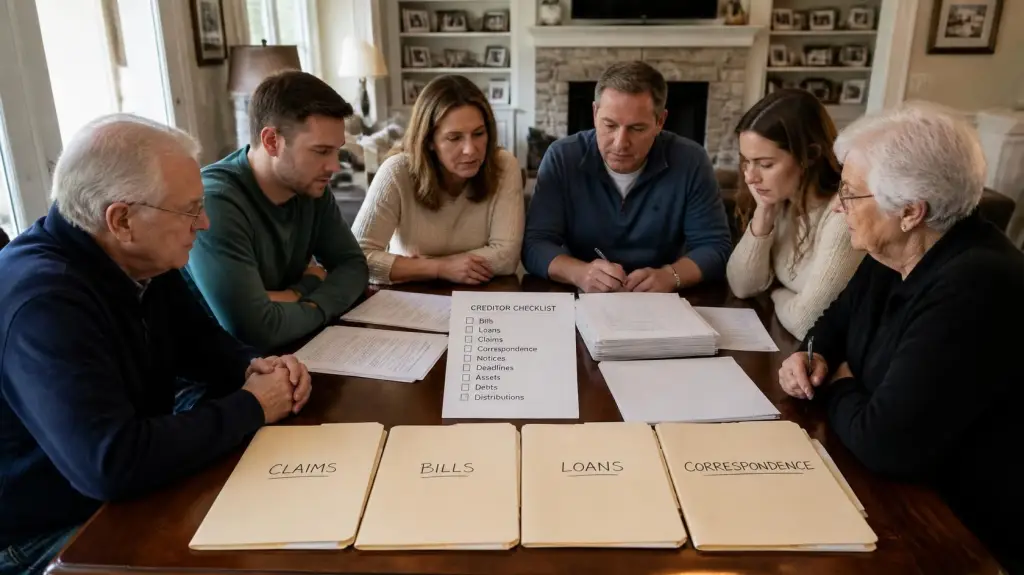
The best time to organize creditor information is before paperwork becomes overwhelming.
Use this checklist as a starting point:
- Gather all bills received after the death.
- Find recent bank and credit card statements.
- Make a list of known creditors.
- Record account numbers.
- Save every collection letter.
- Separate secured debts from ordinary bills.
- Identify accounts held jointly with another person.
- Identify loans with co-signers.
- Give creditor information to the personal representative.
- Keep copies of all correspondence.
- Record the date of each creditor contact.
- Keep receipts for authorized estate payments.
- Do not promise personal payment without understanding the legal consequences.
- Ask questions about unfamiliar or disputed claims.
- Consult a qualified Georgia probate professional when the estate involves substantial debt or complicated ownership.
These steps matter because creditor claims against an estate can affect how much property remains for heirs and beneficiaries.
If your family has several unpaid bills or creditor letters, create the creditor list now. A clear list gives the personal representative a better starting point for estate administration and makes it easier to identify unresolved issues.
Read our blog Handling Bills During Probate to understand who pays the bills after someone passes away. Learn the rules for claims against an estate and how it establishes protections and procedures for the executor or administrator under Georgia law.
What Happens if the Estate Does Not Have Enough Money?
Sometimes an estate has more debts than available assets.
This situation can be especially difficult for families because they may expect to inherit property but discover that creditor claims and estate expenses must be addressed first.
The answer is not simply for the family to divide the debts among themselves.
Instead, the personal representative generally needs to administer the estate according to the applicable Georgia rules governing debts, claims, expenses, and distribution.
Georgia law contains specific provisions addressing claims against estates and the administration of estate obligations.
Families should therefore be cautious about distributing estate assets before creditor issues have been properly reviewed.
For example, giving away estate property early could create problems if the estate later needs those assets to satisfy legitimate obligations.
When an estate is insolvent or close to insolvent, professional advice can be particularly important.
What If the Creditor Claim Is Disputed?
A disputed claim may involve the amount, the identity of the debtor, the validity of the debt, or the documentation supporting it.
The personal representative should not treat every disagreement as a reason to ignore the creditor. Instead, the claim should be documented and evaluated.
Depending on the situation, the estate may need additional records, account statements, contracts, invoices, insurance information, or other evidence.
If the disagreement could affect substantial estate property, legal advice may be appropriate.
What About Secured Debts?
Not all debts operate the same way.
A mortgage or vehicle loan may be connected to specific property. This means the family should not treat a secured debt exactly like an ordinary credit card balance.
For example, if a home is subject to a mortgage, the estate and interested family members may need to understand the loan, payment status, ownership, and plans for the property.
Similarly, a vehicle loan can involve both the debt and the vehicle securing it.
Because secured debts can affect important family property, notices involving a home or vehicle should be addressed promptly.
What Should Families Keep From Creditors?
Good records can make probate much easier.
Families should preserve:
- Original creditor letters
- Copies of statements
- Copies of bills
- Account information
- Loan agreements
- Payment records
- Insurance correspondence
- Written disputes
- Creditor responses
- Proof of payment
- Notes from telephone calls
- Court documents
- Probate documents
The purpose is not to keep paperwork forever without a plan. Instead, records allow the personal representative to show what was received, what was investigated, and what action was taken.
Frequently Asked Questions About Creditors During Probate?
Do creditors get paid during probate?
Potentially, yes. Valid debts and claims may be paid from estate assets according to the applicable probate process and Georgia law. The personal representative generally handles estate administration rather than individual family members simply paying debts from personal accounts.
Who is responsible for a deceased person’s debts in Georgia?
The answer depends on the debt and the people legally connected to it. The estate may be responsible for valid debts, while a joint borrower, co-signer, or other legally obligated person may have separate responsibility.
Can creditors contact the executor?
Yes. Georgia consumer guidance specifically recognizes that a debt collector may discuss an alleged debt with an executor of an estate.
Does being an executor mean I personally owe the debt?
Not automatically. Serving as an executor or personal representative is an estate-administration role. Personal liability depends on separate legal circumstances, such as a person’s own contractual obligation.
Should family members pay estate debts with their own money?
Families should not assume that they must use personal funds. If someone voluntarily pays an estate expense, careful records should be kept, and professional advice may be appropriate regarding reimbursement and proper estate accounting.
What happens if a creditor sends a bill after probate begins?
Keep the bill and provide it to the personal representative. The claim can then be reviewed as part of estate administration.
Can a creditor make a false or incorrect claim?
A creditor’s demand is not necessarily proof that the estate owes the amount claimed. Supporting records can be requested and reviewed. Georgia law provides mechanisms concerning notification and proof of creditor claims.
What if a debt collector threatens the family?
Debt collectors are subject to laws restricting certain deceptive, unfair, and abusive collection practices. Georgia’s Attorney General provides consumer information about debt collection rights and complaint procedures.
If the situation involves threats, litigation, substantial money, or uncertainty about personal liability, professional legal advice may be appropriate.
How long can creditors make claims?
Georgia has specific statutory rules concerning creditor claims and estate administration. Families should not rely on a general rule of thumb because deadlines and procedures can depend on the circumstances and the type of estate proceeding.
What if there are no assets to pay the creditors?
An estate with insufficient assets requires careful administration. The family should not assume that relatives must personally pay the difference. The personal representative should determine how the estate’s assets and claims are handled under applicable law.
Final Thoughts: Helping Families Navigate Estate Creditors
Understanding Creditors During Probate does not have to be overwhelming.
The most helpful approach is to slow down, organize the paperwork, and understand the difference between an estate obligation and a family member’s personal obligation.
When a creditor sends a letter, save it.
When a collection agency calls, document the conversation.
When a bill seems unfamiliar, investigate it.
When a debt is large or disputed, seek appropriate guidance.
Most importantly, remember that estate administration exists to provide a structured process for handling the deceased person’s property, debts, claims, and eventual distribution.
For Georgia families, the personal representative is an important part of this process. That person should keep careful records, communicate appropriately with creditors, and avoid distributing estate assets before the estate’s obligations have been properly addressed.
The goal is not to make creditors the center of the probate process. Instead, the goal is to make sure legitimate debts are handled correctly while protecting the estate and the people who have a legal interest in it.